There is a version of financial control that looks, from the outside, like a couple who has simply divided responsibilities. One person handles the money. The other handles something else. The arrangement feels practical, even considerate, until the person who does not handle the money realises they cannot buy a train ticket without asking, cannot know what is in the account, and cannot remember the last time they had cash of their own.
That is where the line sits, not in who manages the finances, but in whether both people can access money freely, know what the household has, and make decisions without fear of the consequences.
What Financial Control Actually Looks Like
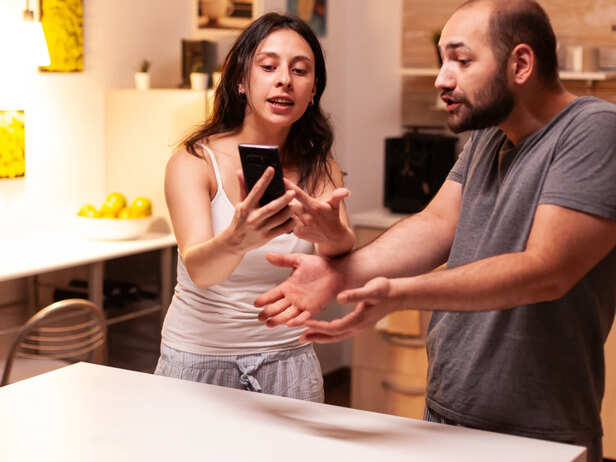
![Couple fight]()
Couple fight
Image credit : Freepik
It rarely announces itself. The more common pattern is a series of small adjustments, each of which has a reasonable-sounding explanation at the time. An account gets moved to one name because it is simpler. A card gets cancelled because of overspending. A purchase gets questioned once, then regularly, then always. The partner who is being controlled often internalises the logic before they notice the pattern.
Some of the clearest signs: having to account for every purchase in detail, being given an allowance by an adult partner, not knowing what the household earns or owes, having your name removed from accounts you once shared, being told you are bad with money so often that you begin to believe it, and feeling genuine fear about what will happen if you spend something without permission.
The fear is the signal. Disagreement about spending is ordinary in any relationship. Fear of a partner's reaction to a small, ordinary purchase is not.
Why It Escalates Slowly
Financial control works partly because it is incremental. Each step is small enough to explain away and large enough to matter. By the time the pattern is visible, the person on the receiving end has often lost access to the practical things that would make leaving easier, their own account, their own income history, their own knowledge of what the household owns.
It also works because it is invisible to people outside the relationship. There are no marks. There is no incident that a friend witnesses. What there is, instead, is a person who always says they need to check with their partner before agreeing to anything, who never seems to have money on them, who changes the subject when finances come up.
The gradual nature of it means that the person experiencing it often does not name it as control for a long time. They name it as their partner being careful, or anxious, or better at this than they are. Naming it accurately is not a small thing, it is usually the first thing.
The Connection to Other Control
![Spending quality time]()
Spending quality time
Image credit : Freepik
Financial control rarely exists on its own. It tends to sit alongside other forms of control, over movement, over friendships, over how someone dresses or speaks. Money is effective as a control mechanism precisely because it limits options. A person who cannot access funds cannot easily leave, cannot consult a lawyer, cannot book a hotel room, cannot take a day off work to sort something out.
This is worth understanding not to make the situation feel more frightening, but because it explains why financial control is taken seriously as a form of coercion rather than treated as a domestic disagreement about budgeting. The effect is the same whether or not the intent is conscious: it narrows the other person's world.
What Practical Steps Exist
The steps that matter most depend on where someone is in recognising what is happening. For someone who is still uncertain, the most useful thing is usually to talk to someone outside the relationship, a trusted friend, a family member, or a counsellor, not to be told what to do, but to hear the situation described back in plain words.
For someone who is clear about what is happening and thinking about what comes next, a few things are worth knowing. Opening a separate account in your own name, at a different bank from any shared accounts, is legal and private. Gathering documents, identity papers, any financial records you have access to, anything with your name on it, and keeping them somewhere safe outside the home is a practical step that does not require a decision to leave. Knowing what income, assets, and debts exist in your name is information you are entitled to.
In India, financial abuse within a domestic relationship falls under the Protection of Women from Domestic Violence Act, 2005, which recognises economic abuse explicitly as a form of domestic violence. This means legal remedies exist, including the right to residence and maintenance orders. A lawyer who handles family law can explain what applies to a specific situation. Legal aid is available through district legal services authorities for those who cannot afford private counsel.
National Commission for Women and state women's commissions maintain helplines. iCall, a psychosocial helpline run by TISS, offers counselling. Local NGOs working on domestic violence, organisations like Majlis in Mumbai, Sakhi in Delhi, or Swayam in Kolkata, provide both legal and emotional support, and many offer confidential first conversations without any commitment to a course of action.
What Helping Someone Else Looks Like
If you are reading this because you are worried about someone you know, the most useful thing is not to tell them what to do. People in controlling relationships already have someone telling them what to do. What is more useful is to stay present, keep the friendship or contact alive even when they seem to pull away, and make clear, once, plainly, without pressure, that you are someone they can call. Offering practical help, like being a safe place to store documents or a person who can receive a call at any hour, is more useful than an ultimatum about what they should decide.
Financial control tends to isolate people. The antidote to isolation is a connection that stays open.
Financial control is coercive because it limits options, not because it raises its voice. The moment someone begins to see the pattern clearly, to name it as control rather than as their partner's personality, is the moment the options begin to come back into view. They were always there. They were just made harder to reach.
Are relationship issues affecting your peace of mind? Your name energy may be playing a role. Check your name energy here!Unlock insightful tips and inspiration on personal growth, productivity, and well-being. Stay motivated and updated with the latest at
My Life XP.
.